

Blogs
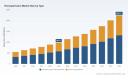
The market revenue for Wireless Data Radio Modems in China is projected to grow from USD 220 Million in 2020 to approximately USD 520 Million by 2035. Robust industrial automation, IoT proliferation, and expansion of smart infrastructure projects are driving long-term revenue growth. This upward trend reflects strong government support and increased private investment, especially in precision agriculture, urban transport, and smart utility networks. The steady rise in revenue year-on-year signals sustained adoption of wireless communication technologies across China’s critical sectors.
Read More - https://bussinessinsights.com/research-report/china-wireless-data-radio-modem-market
SCADA & Telemetry applications are the largest contributors to the China Wireless Data Radio Modem market in 2025, accounting for over a third of total usage. Precision Farming and Transportation segments are rapidly expanding, driven by nationwide digitization and infrastructure upgrades. Power Distribution, Point of Sale, and other emerging applications also add to the market’s diversity. The growing prevalence of telemetric solutions and automated monitoring systems in critical infrastructure and agriculture underpins the market’s resilience, further boosted by ongoing investments in smart cities and rural digitization.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-wireless-data-radio-modem-market
Frequently Asked Questions
Who are the key players in China Wireless Data Radio Modem Market industry?
The top five players in the China Wireless Data Radio Modem Market are Digi International, Advantech, SATEL, Campbell Scientific, and Beijing Gaoke. These companies lead with innovation in wireless communication solutions, extensive distribution networks, and strong R&D, serving industrial automation, transportation, and smart city projects across China.
What is the China Wireless Data Radio Modem Market growth?
The China Wireless Data Radio Modem Market is witnessing robust growth, driven by increasing adoption in industries like utilities and transportation. For instance, Advantech reported a significant rise in demand for wireless modems used in smart grid and railway signaling systems, boosting overall market expansion in 2023.
Which segment accounted for the largest China Wireless Data Radio Modem Market share?
The industrial automation application segment holds the largest market share within China’s wireless data radio modem market. This dominance is fueled by the integration of wireless communications for process control, monitoring, and data acquisition across manufacturing industries striving for digital transformation and operational efficiency.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Earthing Lightning Protection Market to Hit $10.61B by 2032 at 7.3% CAGR
By PW Consulting, 2026-09-16
Navigating the Surge: Strategic Intelligence for the Earthing Lightning Protection System Market in 2026
The global infrastructure landscape is undergoing a critical transformation, driven by the accelerating need for resilient electrical safety systems. As we move deeper into 2026, the Earthing Lightning Protection System Market stands at a pivotal juncture where historical growth trajectories meet new regulatory and technological realities. For industry stakeholders, investors, and strategic planners, understanding the nuances of this evolution is not merely an academic exercise—it is a fundamental requirement for risk mitigation and capital allocation.
This article serves as an executive overview of the comprehensive market research recently published by PW Consulting. Our analysis draws upon a robust dataset spanning from 2020 through 2025, offering a detailed forecast window extending to 2032. The objective is to arm decision-makers with the foresight necessary to navigate a market defined by stringent compliance standards, material innovations, and shifting geographic demands. The following insights represent the high-level strategic value embedded within our full report, highlighting why deep-dive intelligence is essential for capturing the opportunities within this sector.
Lightning Arrester Market
Market Trajectory and Financial Horizons
The financial architecture of the Earthing Lightning Protection System Market demonstrates a consistent upward trend, reflecting the global prioritization of infrastructure safety. Our research indicates that the overall market revenue has seen steady expansion over the past half-decade. Starting from a baseline in 2020, the market has cultivated substantial momentum, reaching significant valuation milestones by 2025. This historical performance sets the stage for a forecast period that analysts view with considerable optimism.
Looking toward the immediate and long-term future, the growth trajectory suggests a compound annual growth rate (CAGR) that underscores the sector's vitality. This expansion is not accidental; it is the result of compounded investments in industrial safety, renewable energy integration, and telecommunications infrastructure. However, raw numbers alone do not tell the whole story. The strategic value lies in understanding the velocity of this growth and the specific drivers that will sustain it beyond 2026. Our report dissects these financial flows to reveal where capital is concentrating and where future revenue streams are likely to emerge, providing a clear lens through which to view investment potential.
Regulatory Frameworks as Growth Engines
One of the most potent catalysts for market expansion is the evolving landscape of international safety standards. Compliance is no longer optional; it is a prerequisite for market entry and operational continuity in many regions. The industry is heavily influenced by established protocols such as the IEC 62305 series, which mandates comprehensive earthing and lightning protection systems for structures and electrical installations. Similarly, the UL 96A standard establishes rigorous requirements for the installation of lightning protection systems, including grounding electrodes, specifically targeting commercial and industrial applications.
These regulations create a structured environment where compliance drives demand. For manufacturers and service providers, alignment with standards like NFPA 780 and UL 96A is critical. Our analysis explores how these regulatory frameworks vary by region and application, creating unique barriers to entry and opportunities for specialization. Companies that can navigate this complex compliance web effectively are positioned to capture greater market share. The report details how these standards influence design choices, material specifications, and installation protocols, ensuring that stakeholders understand the operational implications of regulatory adherence.
Technological Innovations and Material Science
Beyond regulation, the market is being reshaped by advancements in material science and product design. The performance of earthing systems relies heavily on the resistivity of the ground and the conductivity of the materials used. Industry data highlights the importance of copper bonded electrodes in maintaining low resistance grounding performance, often requiring systems to achieve thresholds below 10 ohms. Furthermore, copper conductors and plates are frequently specified for earthing systems to achieve even stricter grounding resistance targets, such as below 4 ohms, in lightning protection setups.
Recent developments indicate a shift toward more application-specific solutions. For instance, recent product announcements have showcased retractable grounding assemblies for storage tanks, addressing niche requirements within oil and gas facilities. Additionally, the release of comprehensive product catalogs and design tools is streamlining the engineering process for contractors and engineers. These innovations reduce installation time and improve reliability, which in turn accelerates adoption. Our research evaluates these technological shifts to determine which innovations are likely to become industry standards and which represent transient trends. Understanding the technical specifications behind these products is crucial for procurement teams and engineering leads.
Competitive Landscape and Key Players
The market structure is characterized by a mix of established multinational corporations and specialized regional manufacturers. Our analysis identifies key companies that are defining the competitive boundaries. These entities range from manufacturers of structural lightning protection components and grounding electrodes to providers of application-specific systems and surge protection integration.
Leading players such as nVent ERICO and DEHN SE are recognized for their specialist capabilities in integrating lightning protection with surge suppression and compliance standards. Meanwhile, firms like Harger Lightning and Grounding and Lightning Eliminators focus heavily on structural components and application-specific assemblies, particularly in the North American market. Other significant contributors include Furse and LPI Group, which provide complete systems across Europe and the UAE, and regional powerhouses like Gravin Earthing & Lightning Protection System and Bahra Electric, which serve specific material and geographic needs.
The competitive dynamics are further influenced by the low market concentration, suggesting ample opportunity for new entrants or niche players who can differentiate through technology or service. Our report provides a detailed competitive benchmarking analysis, evaluating the strategic moves, product launches, and standard updates undertaken by these key entities. By understanding the strategies of these market leaders, organizations can better position themselves to compete or collaborate effectively.
Strategic Segmentation and Application Drivers
Demand for earthing and lightning protection is not uniform across all sectors. The market is segmented by type, region, and application, each with its own growth drivers. The division between Lighting Protection Systems and Earthing Systems represents a fundamental split in product focus, with both segments contributing significantly to overall revenue. However, the application side offers deeper insights into where the immediate demand lies.
Key application areas include industrial factories, solar plants, telecommunications towers, residential homes, and the oil and gas sector. Each of these verticals faces distinct risk profiles and compliance requirements. For example, solar plants require robust earthing to protect significant capital investment in photovoltaic arrays, while factories demand systems that can handle high-voltage industrial loads. Telecom towers, often located in exposed areas, rely heavily on effective lightning protection to ensure network uptime. Our report breaks down these application drivers to reveal which sectors are experiencing the highest velocity of adoption. We analyze the specific needs of each vertical without disclosing the precise revenue splits, encouraging stakeholders to consult the full dataset for actionable allocation strategies.
Earthing Lightning Protection System Market
Regional Dynamics and Growth Variations
Geography plays a crucial role in market performance. Different regions exhibit varying levels of infrastructure development, regulatory strictness, and climatic conditions that influence lightning risk. The market is distributed across major global regions, including North America, Europe, Asia Pacific, Latin America, and the Mideast and Africa.
Asia Pacific, for instance, represents a significant portion of the market volume, driven by rapid industrialization and infrastructure projects. North America and Europe maintain strong demand due to mature regulatory environments and the retrofitting of existing structures. Emerging markets in Latin America and the Mideast and Africa present growth opportunities linked to energy projects and urban development. However, navigating these regions requires an understanding of local standards and supply chain logistics. Our comprehensive study maps these regional nuances, offering guidance on where to focus sales efforts and distribution networks. We highlight the macro trends in each geography while reserving specific regional revenue figures for the detailed report to ensure clients benefit from the complete intelligence package.
Market Concentration and Consolidation Trends
An important aspect of the competitive environment is the level of market concentration. Current data suggests a fragmented landscape where no single entity dominates the entire value chain. This fragmentation indicates that while large players hold significant influence, there is substantial room for competition based on quality, innovation, and regional expertise.
This structure impacts pricing power, supply chain resilience, and merger and acquisition strategies. Companies looking to expand may find opportunities to consolidate smaller regional players to gain market access. Conversely, smaller firms may seek partnerships with larger integrators to broaden their solution offerings. Our analysis examines the implications of this concentration level, providing context for strategic partnerships and M&A activities. Understanding the balance of power among the top competitors is essential for forecasting market stability and pricing trends.
In conclusion, the Earthing Lightning Protection System Market offers substantial opportunities for those equipped with the right intelligence. The convergence of regulatory pressure, technological advancement, and infrastructure development creates a fertile environment for growth. However, realizing this potential requires more than a surface-level understanding of the market. It demands a deep dive into the specific drivers, competitive maneuvers, and regional intricacies that define the landscape.
This article has provided a strategic overview of the key themes shaping the industry in 2026 and beyond. Yet, the full extent of the opportunity lies in the details. The complete PW Consulting market research report offers exhaustive data, precise segmentation analysis, and actionable forecasts that go beyond the macro trends discussed here. For enterprises ready to make informed decisions on product development, market entry, or investment, accessing the full intelligence is the critical next step. We invite you to explore the complete study to unlock the comprehensive insights necessary to lead in this evolving market.
For detailed analysis of this topic, please visit the official page: Earthing Lightning Protection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China application processor market is projected to grow from USD 22,300 million in 2020 to USD 38,750 million by 2035. This steady upward trajectory highlights rising consumption across mobile, automotive, wearable, and smart home sectors. Driven by 5G rollouts, local manufacturing pushes, and growing demand for AI-enabled devices, the market sustains a healthy CAGR. Despite short-term challenges, long-term prospects remain robust as processor integration deepens in key consumer and industrial sectors.
Read More - https://bussinessinsights.com/research-report/china-application-processor-market
Smartphones dominate application processor consumption in China, constituting nearly half of total market share in 2025 due to the nation’s high smartphone penetration and upgrade cycles. Automotive applications are rapidly rising, fueled by connected cars and infotainment, while wearables and IoT devices account for notable portions, reflecting their integration in daily life. This division reflects a broadening use-case landscape, highlighting industry diversification beyond traditional mobile devices.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-application-processor-market
Frequently Asked Questions
Who are the key players in China Application Processor Market industry?
The top 5 players in the China Application Processor Market are HiSilicon (Huawei), MediaTek, Qualcomm, UNISOC, and Apple. HiSilicon is renowned for its Kirin chipsets, MediaTek for competitive SoCs in mid-range devices, Qualcomm supplies Snapdragon processors, UNISOC focuses on cost-effective solutions, and Apple’s custom silicon powers its iPhones.
What is the China Application Processor Market growth?
The China Application Processor Market has seen significant growth, especially in 2023, driven by the rollout of 5G smartphones and rising IoT adoption. HiSilicon and MediaTek reported strong revenue growth as domestic brands accelerated chip integration, fostering technological independence amidst global supply chain shifts.
Which segment accounted for the largest China Application Processor Market share?
The smartphone application segment holds the largest market share in China. With over 70% share, demand is propelled by fast smartphone replacement cycles and innovation in mobile devices. Leading brands such as Xiaomi, OPPO, and Vivo have contributed to application processors’ dominance in this segment.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
The China Smart Thermostat Market is forecasted to see strong revenue growth, rising from USD 380 Million in 2020 to an estimated USD 1,535 Million by 2035. Growth is propelled by urbanization, technological advancements, and supportive government initiatives. The market experienced steady increases year over year, with major acceleration observed post-2025 as smart home adoption scales and commercial retrofits accelerate. Improved device interoperability, energy-saving mandates, and consumer focus on convenience bolster revenue momentum through the forecast period, confirming this sector as a key pillar of China’s smart city evolution.
Read More - https://bussinessinsights.com/research-report/china-smart-thermostat-market
Residential applications represent 44% of the total market, underlining growing demand from individual homeowners across urban China. Commercial installations stand at 30%, driven by smart building trends and regulatory energy mandates for office spaces. The industrial segment, including healthcare and hospitality facilities, accounts for 18%, supported by infrastructure modernization and sustainability goals. The remainder comes from emerging applications in public and institutional buildings, signaling untapped potential for future expansion—especially as smart climate control becomes integral in multiple sectors.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-smart-thermostat-market
Frequently Asked Questions
Who are the key players in China Smart Thermostat Market industry?
The top 5 players in the China Smart Thermostat Market are Haier, Xiaomi, Huawei, Schneider Electric, and Honeywell. These companies are known for innovation, extensive product lines, and strong market presence, driving the adoption of smart home technologies through advanced thermostats tailored to the growing Chinese consumer base.
What is the China Smart Thermostat Market growth?
The China Smart Thermostat Market has witnessed robust growth, with a CAGR of over 20% from 2022 to 2024. This growth is driven by smart home adoption, government energy efficiency initiatives, and new product launches by companies such as Xiaomi and Haier, making smart thermostats increasingly accessible.
Which segment accounted for the largest China Smart Thermostat Market share?
The residential application segment holds the largest share in the China Smart Thermostat Market. Increased demand for smart home automation, ease of climate control, and energy-saving features in households have fueled this segment’s expansion, especially as urbanization and technological awareness rise among Chinese consumers.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Photocatalyst Market Hits $2.2B in 2025, Forecasts 9.6% CAGR to $4.18B by 2032
By PW Consulting, 2026-09-16
The Photocatalyst Market in 2026: A Strategic Compass for Industrial Transition
The global photocatalyst market stands at a pivotal inflection point. After a decade of incremental adoption driven by niche environmental applications, the sector is now accelerating under the combined weight of regulatory pressure, urban air-quality mandates, and next-generation construction standards. Our latest market research delivers a comprehensive, forward-looking assessment of this landscape, designed specifically to equip corporate strategists, R&D directors, and investment committees with the operational intelligence needed to navigate decision-making in 2026 and beyond.
By consolidating five years of historical performance with a seven-year forecast horizon, the study maps how demand is structurally shifting across material classes, end-use sectors, and regional ecosystems. More importantly, it translates macro trajectories into actionable strategic frameworks—covering supply-chain resilience, regulatory compliance pathways, competitive positioning, and innovation roadmaps. This is not a static sizing exercise. It is a decision-support architecture for enterprises that must anticipate where capital, technology, and policy will converge over the next cycle.
A Market Accelerating Under Structural Tailwinds
Photocatalysis has evolved from a laboratory-scale environmental concept into a commercially embedded technology set. The sector’s valuation trajectory over the past half-decade reflects a clear acceleration, with revenue compounding steadily from the early 2020s through the current base year. That momentum is projected to intensify as the forecast window unfolds, supported by a compound annual growth rate that places the industry among the faster-growing segments within advanced materials and environmental technologies.
The underlying drivers are multifaceted and mutually reinforcing. Stricter indoor-air VOC and NOx emission standards worldwide are pushing facility operators, architects, and municipal authorities toward photocatalytic air-purification and self-cleaning materials. Simultaneously, the European Green Deal’s circular-economy provisions are channeling subsidies into sustainable construction materials that incorporate photocatalytic glazing and surface treatments. These policy signals are not isolated; they are compounding with corporate sustainability commitments, urbanization pressures, and a growing recognition that passive environmental remediation can deliver measurable operational savings over asset lifecycles.
Precious Metal Catalyst Market
Yet growth is not uniform, and the strategic implications vary sharply by material type, application architecture, and geographic footprint. This is precisely where high-level headlines fall short and granular, structured analysis becomes essential. Our research dissects the market’s composition without exposing the margin for guesswork, allowing leadership teams to evaluate where their portfolios align with the steepest growth vectors and where exposure to slower-moving segments requires defensive repositioning.
Photocatalyst Market
From Macro Trajectories to Operational Strategy
The study is structured to bridge the gap between top-line market direction and on-the-ground execution. Rather than presenting a single aggregate figure, the report builds a layered view of demand dynamics, pricing behavior, and technology substitution patterns across the forecast horizon. It examines how input-cost volatility—particularly within high-purity titanium dioxide feedstock supply chains, where production remains concentrated among a limited number of global suppliers—shapes margin structures and procurement strategies for downstream formulators and coating manufacturers.
Supply-chain visibility is a recurring theme. The analysis maps the sensitivity of photocatalytic product economics to upstream raw-material availability, logistics bottlenecks, and regional production capacity. It also evaluates how vertical integration moves by key feedstock and intermediate suppliers influence stability of supply and cost predictability for industrial buyers. For procurement and operations teams, these insights translate into more resilient sourcing frameworks and better-informed make-versus-buy decisions for specialty formulations.
On the demand side, the report traces how application adoption curves diverge across sectors. Air purification, water purification, and self-cleaning surfaces each follow distinct commercialization rhythms, shaped by local regulatory timelines, public-sector procurement cycles, and building-material integration requirements. Anti-fogging and anti-soiling coatings, alongside other emerging use cases, occupy a different risk-reward profile, typically requiring longer validation periods but offering higher differentiation potential once performance thresholds are met. The study outlines the commercial milestones, testing protocols, and certification pathways that govern market entry, helping R&D and product management teams sequence development pipelines against realistic adoption windows.
The forecast framework extends through the end of the decade and into the early 2030s, enabling scenario planning under varying assumptions for regulation, feedstock costs, and regional investment intensity. By modeling how different policy or cost environments could alter demand pacing, the report equips strategy teams to stress-test capital allocation, capacity expansion, and partnership choices well ahead of market inflection points.
Competitive Architecture and the Players Shaping the Next Cycle
The competitive landscape in photocatalysis is defined by a blend of material science specialists, large chemical conglomerates, and application-focused innovators. Concentration metrics indicate that the top three and top five participants command a meaningful share of commercial activity, underscoring the importance of understanding not just who leads today, but how incumbency advantages, differentiation strategies, and partnership ecosystems are evolving.
Kronos Worldwide, Inc. remains a specialist in photocatalytic titanium dioxide grades tailored for self-cleaning surfaces and building materials, positioning its portfolio around architectural and infrastructure demand. Cristal Global, operating through its CristalACTiV platform, has advanced ultrafine titanium dioxide formulations for photocatalytic coatings and NOx abatement applications, with recent product development centered on air-quality improvement use cases. TOTO Ltd. supplies photocatalytic coatings spanning self-cleaning surfaces as well as air and water purification, with a strong footprint in construction and healthcare environments. Ishihara Sangyo Kaisha, Ltd. contributes high-purity titanium dioxide photocatalysts aimed at environmental and industrial applications, while Nippon Soda Co., Ltd. develops and supplies photocatalytic formulations and binders that enable downstream integration.
On the broader materials and environmental catalysis side, BASF SE provides photocatalytic materials for air purification and environmental catalysis, leveraging its scale and cross-sector distribution capabilities. In the innovation frontier, Puralytics LLC has developed PuraMesh photocatalyst technology for advanced oxidation and water/air purification, while Nanoptek Corp. supplies visible-light titania photocatalysts and pigments that address performance limitations in lower-light conditions. Daicel Miraizu continues as a manufacturer of photocatalytic materials and coatings, and the International Photocatalyst Standards Test Centre in the UK serves as an independent testing and certification provider, underpinning market credibility through ISO-aligned evaluation protocols.
Recent corporate activity reinforces the strategic direction of the sector. In early 2026, Cristal Global advanced its CristalACTiV TiO2 products for NOx abatement applications targeting air-quality improvement, signaling continued emphasis on pollution-mitigation endpoints. Around the same period, Tronox highlighted photocatalytic applications within its specialty TiO2 products in its sustainability reporting, while also advancing vertical integration in its TiCl4 supply chain to stabilize TiO2 production. These moves illustrate a broader pattern: leading participants are aligning product development with regulatory tailwinds, while simultaneously working to insulate production from feedstock volatility.
The report examines how these competitive dynamics translate into market access barriers, partnership opportunities, and differentiation strategies. It evaluates where scale, where formulation expertise, and where application validation create durable advantages, and where new entrants or collaborative models may compress incumbency moats over the forecast period.
Why 2026 Is a Decision Window, Not Just a Forecast Year
For corporate decision-makers, 2026 functions as a strategic checkpoint. The convergence of tighter emission standards, subsidy mechanisms for sustainable construction, and evolving testing and certification expectations is reshaping the criteria by which photocatalytic products win commercial adoption. Enterprises that treat this year as a passive continuation of prior trends risk misaligning product roadmaps, sourcing strategies, and go-to-market priorities with the market’s actual direction.
Notable structural forces now shaping that direction include the ongoing influence of environmental compliance on specialty TiO2 product portfolios, with sustainability reporting and regulatory expectations encouraging broader adoption of photocatalytic NOx abatement technologies. In parallel, European frameworks are directing financial support toward circular-economy-aligned building materials, strengthening the economic case for photocatalytic glazing and surface solutions. At the same time, global indoor-air quality standards are tightening, expanding the addressable base for photocatalytic air-purification and self-cleaning materials. Regulatory approvals from bodies such as the European Chemicals Agency have also enabled the commercial launch of new photocatalytic products for air purification, widening the field for innovation-led entrants while raising the bar for compliance-ready product design.
These conditions create a market environment where strategic timing matters as much as technical capability. Companies that understand the interplay between feedstock cost dynamics, regional regulatory pacing, and application-specific certification requirements are better positioned to prioritize investments, negotiate supply agreements, and structure partnerships. The study is built to surface those interdependencies clearly, giving leadership teams a shared analytical baseline for cross-functional planning.
What the Report Delivers for Strategy, R&D, and Commercial Teams
The research is organized to support a wide range of internal use cases. For strategy and corporate development teams, it provides a market-level orientation that ties growth trajectories to competitive positioning, enabling more informed evaluation of adjacency opportunities, M&A targets, and geographic expansion priorities. For R&D and product teams, it maps technology substitution patterns, formulation considerations, and performance-testing expectations, helping calibrate development timelines against market readiness. For commercial and sales leadership, it outlines application-specific demand drivers, procurement contexts, and the regulatory and certification factors that influence buying decisions in construction, environmental services, and industrial settings.
The report also includes practical coverage of market-concentration dynamics, supply-chain sensitivity, and recent corporate developments that shape near-term competitive behavior. It integrates sector-level signals around regulation, raw-material availability, and sustainability reporting trends, translating them into implications for sourcing, pricing, and product positioning. By combining historical context, forecast direction, and qualitative intelligence on the companies and institutions actively shaping the market, the study offers a consolidated reference point for decision-making across functions.
Importantly, the analysis is designed to remain useful beyond the immediate planning cycle. Because photocatalytic adoption is influenced by long-duration assets such as buildings, infrastructure, and industrial facilities, today’s product and sourcing choices have multi-year consequences. The forecast horizon and scenario frameworks included in the research help organizations connect near-term actions to longer-term outcomes, reducing the risk of short-horizon optimization that undermines competitive positioning later in the decade.
Accessing the Full Intelligence Suite
Our Photocatalyst Market study is intended for teams that need more than directional commentary. It provides a structured, data-informed foundation for evaluating where the market is heading, which actors are shaping the pace of change, and how enterprise strategy should respond in 2026 and through the coming forecast years. The complete report includes detailed segmentation analyses, competitive profiles, regulatory and supply-chain assessments, and forecast scenarios that together form a comprehensive decision-support toolkit.
To explore the full segmentation detail, company-level positioning, regional demand architecture, and scenario-based forecasts, request access to the complete market research. The full intelligence suite is available through our official research portal, where strategy, procurement, and innovation teams can retrieve the complete dataset and analytical modules needed to ground 2026 planning in a rigorous, forward-looking view of the photocatalyst market.
For detailed analysis of this topic, please visit the official page: Photocatalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The wireless devices market in China has demonstrated consistent revenue growth from 2020 to 2025, with a rapid acceleration projected from 2025 onwards due to increased penetration of 5G networks and industrial IoT. Market revenue is expected to rise from approximately USD 220,000 million in 2025 to over USD 450,000 million by 2035, representing a robust compound annual growth rate. The upward trend is supported by demand from both consumer and commercial applications, as well as continuous product innovation by leading technology companies.
Read More - https://bussinessinsights.com/research-report/china-wireless-devices-market
The consumer electronics segment accounts for the largest proportion of demand in 2025, led by the mass adoption of smartphones, wearables, and smart home devices. Industrial applications show robust growth, driven by advancements in smart factories and automation. Healthcare-related wireless devices, such as remote monitoring wearables and medical IoT sensors, are rapidly increasing in share as digital health receives greater investment. Automotive and retail sectors are also emerging as notable contributors, leveraging real-time communication and smart device integration.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-wireless-devices-market
Frequently Asked Questions
Who are the key players in China Wireless Devices Market industry?
The top 5 players in the China Wireless Devices Market include Huawei Technologies, Xiaomi Corporation, ZTE Corporation, Oppo, and Vivo. These companies are renowned for their innovation in smartphones, 5G equipment, and IoT solutions, capturing substantial market share and continually expanding their product portfolios to meet evolving consumer demand.
What is the China Wireless Devices Market growth?
The China Wireless Devices Market is experiencing robust growth, driven by increased adoption of 5G technology and smart devices. For instance, Huawei reported a surge in its smart device sales in 2023, fueled by government support and rising consumer demand for faster, more reliable connectivity.
Which segment accounted for the largest China Wireless Devices Market share?
The smartphone application segment holds the largest market share in the China Wireless Devices Market. Widespread smartphone adoption, intensive mobile internet usage, and advanced features offered by manufacturers like Xiaomi and Oppo have propelled the growth of this dominant segment.
Thanks & Regards,
Supriya singh
sales@bussinessinsights.com
PW Consulting: Ball Mill Mining Market Hits $4.35B in 2025, Projected to Reach $6.86B by 2032
By PW Consulting, 2026-09-16
Ball Mill (Mining) Market 2026: Navigating the Efficiency Imperative in a $4.6 Billion Industry
The global mining equipment landscape is undergoing a structural transformation, and at the heart of this shift lies the ball mill. As the workhorse of mineral processing, the ball mill remains indispensable for reducing ore to fine particles suitable for downstream extraction. Yet, the operational context surrounding this machinery is changing rapidly. Rising energy costs, stricter environmental regulations, and the relentless pursuit of throughput optimization are reshaping procurement strategies, capex planning, and long-term fleet management for mining enterprises worldwide.
PW Consulting’s latest market research on the Ball Mill (Mining) Market is designed to cut through this complexity. Built on a rigorous historical dataset spanning 2020 through 2025 and extended with a comprehensive forecast period through 2032, this report provides the strategic intelligence required to make high-stakes decisions in 2026 and beyond. The market has demonstrated consistent momentum, with overall industry revenue climbing from 3171.89 million USD in 2020 to an estimated 4353.5 million USD by the base year of 2025. The forward trajectory points to continued expansion, positioning the sector at a projected 4606.46 million USD in 2026, with growth compounding toward 6859.45 million USD by 2032. This expansion is underpinned by a compound annual growth rate of 6.9 percent, reflecting sustained investment in mining infrastructure, the commissioning of new processing plants, and the modernization of aging grinding circuits.
For executives, engineers, and procurement leaders, these aggregate figures serve as a critical baseline. They signal that demand for grinding equipment is not merely cyclical but structurally supported by the global need for processed minerals across industrial, technological, and energy-transition applications. However, aggregate size alone does not dictate strategy. The true value of this research lies in its ability to translate macro trends into actionable frameworks, helping organizations allocate capital, evaluate vendor partnerships, and anticipate regulatory or supply-chain disruptions before they impact operations.
The Strategic Value of Granular Intelligence for 2026 Decision-Making
2026 represents a pivotal planning year for mining organizations. Capital allocation decisions made now will determine operational competitiveness over the next several years, particularly as companies balance throughput targets with escalating energy costs and compliance requirements. The PW Consulting report is structured to support these decisions with field-ready analysis rather than abstract commentary. Readers will find detailed breakdowns of equipment types, end-use applications, and regional deployment patterns, all contextualized within the broader market trajectory.
The research dissects the market across multiple dimensions that matter directly to procurement and engineering teams. Equipment segmentation covers wet grinding ball mills, dry grinding ball mills, and other specialized configurations, allowing readers to understand where demand is concentrating and how technological preferences are evolving. Application-level analysis examines use cases across metal mining, mineral mining, and other processing verticals, highlighting where throughput requirements, liberation size targets, and circuit configurations differ. Geographic coverage spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, providing a global view of where development activity, mine expansions, and equipment replacement cycles are most active.
Importantly, the report does not simply present data points in isolation. Each segment is examined through the lens of operational relevance, helping decision-makers understand why certain configurations are favored in specific contexts, how application requirements drive specification choices, and which geographic markets are experiencing the most intense competition for supply and installation capacity. This approach ensures that readers can map market intelligence directly onto their own asset planning, vendor negotiations, and risk management frameworks.
Competitive Landscape: Established Leaders and Emerging Pressures
The ball mill market is characterized by a moderately concentrated competitive environment, with the top three players accounting for approximately 33.5 percent of market share and the top five collectively capturing around 48.2 percent. This structure creates a landscape where established multinational suppliers compete on technology, reliability, and global service networks, while regional and specialized manufacturers carve out positions through cost efficiency, customization, and responsiveness to local project requirements. Understanding this dynamic is essential for organizations evaluating supplier partnerships, negotiating procurement contracts, or assessing the availability of spare parts and technical support over the lifespan of a grinding circuit.
Several core companies define the current competitive baseline. Metso, headquartered in Finland, has strengthened its position through its Premier and Select horizontal ball mill offerings, emphasizing energy-efficient grinding solutions that can deliver up to 30 percent energy savings compared with conventional ball mills. This focus on efficiency aligns with broader industry mandates and appeals to operators seeking to reduce operating expenditures while maintaining throughput. FLSmidth, based in Denmark, complements this landscape with high-throughput ball mills and its Tower Mill technology for secondary and fine grinding. The company’s push to replace conventional ball mills in iron ore beneficiation, with documented energy reductions in the 25 to 50 percent range, underscores a strategic emphasis on alternative grinding architectures that can outperform traditional designs in specific applications.
KHD Humboldt Wedag, operating from Germany, continues to serve the market with traditional ball mill designs and upgrade packages for existing grinding circuits, targeting stable and efficient performance in mining environments. Sepro Mineral Systems, from Canada, addresses small and medium capacity operations with tyre-drive rotary grinding mills suitable for ball, rod, and pebble charges, offering a practical solution for operators where flexibility and manageable scale are priorities. On the capacity and throughput side, CITIC Limited in China supplies large-capacity ball mills for mining and mineral processing, with an emphasis on high throughput and reliability. Hongxing Machinery, also based in China, provides standard and energy-saving ball mills for ore re-crushing in mineral processing, reflecting the continued importance of cost-competitive equipment in high-volume segments.
Recent market developments illustrate how competitive and project dynamics are evolving in real time. In September 2025, Deccan Gold Mines Limited launched the Altyn Tor Gold Project in Kyrgyzstan, incorporating a ball mill as part of its gold extraction processing infrastructure. This type of project execution signals sustained demand for grinding equipment in gold and base metal operations, particularly where new facilities are being commissioned or existing circuits are being expanded. In July 2025, Gold Rock Projects introduced a new ball mill designed specifically for gold producers, equipped with digital monitoring sensors for real-time performance tracking and automated load control. This development highlights the growing integration of digital instrumentation and automation into grinding equipment, enabling operators to optimize mill performance, reduce manual intervention, and respond more quickly to changes in feed characteristics or circuit conditions.
Competitive pressure is also coming from adjacent technologies. Metso reported record sales of stirred mills in 2025, with more than 20 Vertimill units sold, demonstrating sustained demand for energy-efficient alternatives to conventional ball mills. This trend does not diminish the role of the ball mill, but it does reinforce the need for operators to evaluate the full spectrum of grinding options when designing or upgrading circuits. Decision-makers must weigh capital cost, energy consumption, maintenance requirements, and product size distribution against the specific demands of their ore bodies and processing goals.
Market Dynamics: Efficiency, Regulation, and Supply Chain Volatility
The operational environment for ball mill procurement and deployment is shaped by a convergence of technical, regulatory, and macroeconomic forces. Energy efficiency mandates and sustainability initiatives across the mining sector are accelerating the adoption of energy-efficient grinding systems and automation. Organizations are increasingly scrutinizing the total cost of ownership of grinding equipment, recognizing that energy consumption during operation can dominate lifecycle costs. The projected 25 to 50 percent energy reduction achievable when replacing conventional ball mills with more efficient alternatives has become a compelling value proposition, particularly for operators facing rising power prices or operating in regions with strict carbon and emissions expectations.
Regulatory frameworks are adding further complexity. OSHA noise exposure limits and the EU Occupational Safety and Health Framework Directive establish strict permissible exposure levels for ball mill operations, conditions that are frequently exceeded without mitigation measures. These requirements are driving interest in engineering controls, enclosure improvements, and operational protocols that reduce noise and vibration at the source. At the same time, compliance pressures are encouraging adoption of ISO 14001 environmental management systems, as mining companies seek to standardize their approach to environmental performance, hazard control, and continuous improvement. Equipment suppliers that can support these compliance objectives through design features, documentation, and service integration are likely to gain preference in competitive tenders.
Supply chain volatility presents another critical consideration. Steel grinding media raw material costs account for 55 to 70 percent of manufacturing costs for forged balls used in ball mills, and these costs have experienced volatility of over 25 percent year-on-year in recent years. Such fluctuations directly affect consumable expenses, which are a significant component of grinding circuit operating costs. Operators must factor media cost volatility into their budgeting, negotiate procurement agreements with appropriate flexibility, and evaluate whether certain mill designs or operating strategies can reduce media consumption or extend media life. The interplay between equipment selection, operating parameters, and consumable costs is a central theme in the report’s analysis, helping readers build more resilient cost models.
Forged Steel Grinding Balls Market
Why This Research Matters Now
The ball mill market is not defined solely by equipment sales; it is shaped by the intersection of ore characteristics, processing objectives, energy economics, regulatory compliance, and competitive technology alternatives. The 6.9 percent CAGR reflected in the forecast period signals that demand will continue to grow, but growth alone does not guarantee optimal outcomes for any individual organization. The strategic question for 2026 is not whether the market is expanding, but how to position within it with the right equipment specifications, supplier relationships, and operational strategies.
Ball Mill (Mining) Market
This research provides the analytical foundation to answer that question. It combines historical validation with forward-looking projections, embeds competitive and project-level developments in context, and addresses the operational dynamics that influence procurement and performance. By connecting market size trends with segmentation insights, regulatory drivers, and supply-chain realities, the report equips readers to make decisions with greater confidence and precision.
For organizations planning capital expenditures, evaluating grinding circuit upgrades, or preparing for new project commissions, the full report offers the depth required to move beyond general market awareness into targeted strategy. Explore the complete analysis, including detailed segmentation, competitive profiles, and operational dynamics, by accessing the full market research at the source page.
For detailed analysis of this topic, please visit the official page: Ball Mill (Mining) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Magnesium Carbonate Market Hits USD 307.71 Million in 2025, Poised for 4.7% CAGR Growth Through 2032
By PW Consulting, 2026-09-16
Strategic Intelligence in the Magnesium Carbonate Market: Navigating Growth Through 2032
Executive Overview
The global magnesium carbonate market stands at a pivotal juncture. As of 2025, the sector has demonstrated steady resilience, recovering from minor fluctuations observed in the early 2020s to establish a robust revenue baseline. For enterprise leaders and strategic planners, understanding the trajectory of this essential industrial mineral is no longer optional; it is a critical component of supply chain security, product development, and competitive positioning.
This article serves as a strategic precursor to the comprehensive Magnesium Carbonate Market Research Report published by PW Consulting. Our analysis covers the historical performance from 2020 through 2025 and projects market behavior through the forecast period ending in 2032. The objective is to equip stakeholders with the macroscopic perspective needed to allocate capital efficiently and anticipate regulatory shifts. However, the granular data required for precise operational modeling is reserved for the full intelligence subscription.
Magnesium Carbonate Market
Market Trajectory and Growth Dynamics
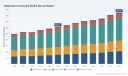
The market has exhibited a consistent upward trend over the past half-decade. Revenue valuations have progressed from approximately 248.5 million USD in 2020 to an estimated 307.71 million USD in 2025. This growth reflects the material's entrenched position in pharmaceuticals, personal care, and industrial manufacturing. Looking ahead, the forecast period from 2026 to 2032 suggests continued expansion, albeit at a measured pace typical of mature commodity markets.
Key macroeconomic indicators derived from our modeling include a projected valuation of 321.45 million USD in 2026, escalating to 424.39 million USD by 2032. This progression implies a Compound Annual Growth Rate (CAGR) of 4.7 percent over the forecast horizon.
- Historical Stability: The market navigated post-pandemic supply chain adjustments between 2020 and 2023, stabilizing at 281.02 million USD by 2023.
- Forecast Momentum: Growth is expected to accelerate slightly in the late forecast period, with significant valuation jumps observed in the 2030 to 2032 window.
- Revenue Scale: All valuations are denominated in USD Millions, providing a standardized metric for cross-regional comparison.
While these headline figures provide a top-down view of market health, they do not reveal the underlying drivers of regional disparity or application-specific demand spikes. Understanding where the growth originates requires a deeper dive into segmentation that only the full report provides.
Segmentation Insights: Type and Application
Magnesium carbonate is not a monolithic commodity. Its utility varies significantly based on physical properties, specifically the distinction between light and heavy grades. Light magnesium carbonate, known for its high porosity and oil absorption capabilities, typically commands a different market dynamic compared to heavy magnesium carbonate, which is often preferred for specific industrial densities and pharmaceutical fillers.
Our analysis indicates that both types contribute substantially to the overall revenue pool. Light magnesium carbonate maintains a significant share of the global revenue, driven by its versatility in personal care and specialty chemical applications. Heavy magnesium carbonate complements this by serving specific industrial and technical requirements. The interplay between these two types dictates pricing strategies and inventory planning for manufacturers.
On the demand side, the application landscape is diverse. The pharmaceutical sector remains a cornerstone consumer, utilizing the material for antacids, laxatives, and tablet excipients. Simultaneously, the rubber and plastic industry leverages magnesium carbonate as a functional filler to enhance durability and processing characteristics. Personal care and cosmetics represent a high-value segment where purity standards are stringent, while the remaining broader industrial applications provide a stable baseline demand.
Calcium Carbonate Market
Note: Precise revenue splits for each type and application segment are proprietary data points within our full database. Stakeholders requiring specific volume or value allocations for these segments to build financial models are encouraged to access the complete segmentation tables in the final report.
Regional Landscape and Trade Flows
Geographically, the market is distributed across five key regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. The Asia Pacific region typically exhibits the highest aggregate volume due to the concentration of manufacturing capacity and raw material availability. North America and Europe maintain mature markets with high demand for high-purity pharmaceutical and food-grade variants.
Trade dynamics play a crucial role in shaping regional supply. For instance, natural magnesium carbonate imports into Japan from China have shown significant valuation in recent trade data, highlighting the interdependence of Asian supply chains. Meanwhile, regulatory frameworks in the United States continue to influence market entry costs and classification standards.
- North America: A mature market with strong regulatory oversight regarding chemical safety and purity.
- Europe: Focuses on high-value specialty grades, with Germany serving as a hub for production and trading.
- Asia Pacific: Dominates in terms of volume and raw material processing, particularly involving magnesite derived from natural sources.
- Rest of World: Emerging demand centers in Latin America and Africa offer niche opportunities for industrial expansion.
Detailed regional revenue contributions and growth rates are critical for determining market entry strategies. Our full report breaks down the specific valuation and forecast for each region, allowing clients to assess local competitiveness without relying on industry averages.
Competitive Landscape and Key Players
The magnesium carbonate market is characterized by a moderately fragmented structure with a concentration of expertise among specialized manufacturers. The top three players hold a combined market share of approximately 23.5 percent, while the top five entities control around 28.0 percent of the revenue. This suggests that while large players exist, there is significant room for specialized niche providers and traders.
Several key companies define the competitive edge through product purity, capacity expansion, and supply chain integration.
Leading Manufacturers and Traders
- Dr. Paul Lohmann GmbH & Co. KGaA (Germany): A premier producer offering high-purity light, heavy, medium heavy, and specialty grades. Their focus spans pharmaceutical, food, and industrial applications, setting a benchmark for quality consistency.
- Kyowa Chemical Industry Co., Ltd. (Japan): Known for pharmaceutical-grade and high-purity light and heavy magnesium carbonate. Their recent product catalog releases emphasize enhanced purity focus for food additives and personal care.
- Konoshima Chemical Co., Ltd. (Japan): Produces multiple grades including plate-shaped variants, catering to specific chemical and industrial use cases that require unique morphological properties.
- Lehmann & Voss & Co. KG (Germany): A significant supplier and trader. Recent updates include enhanced technical selling capabilities and supply chain optimizations for mineral fillers, positioning them as a key logistics and sourcing partner.
- Grecian Magnesite S.A. (Greece): A major producer leveraging natural magnesite. Their recent commissioning of a second X-ray-based mineral processing line at Yerakini Mines signals a strong commitment to capacity expansion and processing efficiency.
- Yingkou Magnesite Chemical (China): A large-scale producer utilizing natural magnesite, playing a critical role in the global supply volume, particularly for industrial grades.
- Others: Additional players such as Naikai Salt Industries, SCORA S.A.S., and Buschle & Lepper S.A. contribute to the ecosystem with specific focuses on food, nutraceutical, bakery, and refractory applications.
The competitive dynamic is not just about production volume. It is about the ability to navigate regulatory changes and supply chain disruptions. The recent developments observed in late 2025, such as portfolio updates and processing line commissions, indicate that incumbents are actively fortifying their positions against potential market volatility.
Regulatory and Industry Context
External factors significantly influence market fluidity. Regulatory status varies by jurisdiction and application, affecting everything from import duties to product certification.
In the United States, magnesium carbonate is listed under the Harmonized Tariff Schedule Chapter 25, with no specific duties applied in the current framework, facilitating relatively smooth trade flows for imported grades. However, compliance remains key. The material was delisted from U.S. color additive certification requirements in recent regulatory updates, simplifying its use in certain cosmetic applications. Conversely, it remains approved in Codex Alimentarius standards as INS 504(i), ensuring its continued legitimacy in global food supply chains.
Raw material economics also factor into strategic planning. Conservation policies, such as depletion allowances for magnesite and magnesium carbonate, can impact cost structures for domestic producers in regions like the U.S. Understanding these fiscal nuances is essential for accurate margin forecasting.
Our report integrates these regulatory and raw material factors into a holistic market view, analyzing how policy shifts in 2026 and beyond might alter cost bases or demand elasticity.
Strategic Value for 2026 Decision-Making
For C-suite executives, procurement officers, and strategy analysts, the Magnesium Carbonate Market Report offers more than just numbers. It provides a framework for action. The period from 2026 to 2032 is expected to see evolving demands in high-purity sectors alongside steady industrial consumption.
Why this intelligence matters now:
- Supply Chain Resilience: With capacity expansions occurring in Europe and production scaling in Asia, knowing where supply is tightening or easing helps mitigate procurement risk.
- Product Portfolio Alignment: As regulations shift, such as changes in color additive certifications or food safety standards, companies must align their product offerings with compliant grades. Our analysis highlights which grades are gaining regulatory favor.
- Investment Timing: The forecast suggests a notable acceleration in market valuation toward the end of the decade. Identifying the catalysts for this growth allows investors to time market entry or capacity expansion correctly.
- Competitive Benchmarking: Knowing the market concentration and the strategic moves of key players like Grecian Magnesite or Kyowa Chemical allows firms to position themselves defensively or offensively.
The data provided in the summary above serves as a validation of market health. However, the specific drivers—such as exact growth percentages per application segment, detailed regional supply deficits, or proprietary pricing models—are contained within the full intelligence suite. Relying on aggregate data alone can lead to suboptimal strategic decisions in a market where purity premiums and regional logistics costs vary widely.
Conclusion
The magnesium carbonate market is poised for steady growth, underpinned by essential demand in pharmaceuticals, industrial manufacturing, and personal care. With a projected CAGR of 4.7 percent and a total market value expected to exceed 424 million USD by 2032, the opportunity for strategic expansion is clear.
However, success in this market requires more than a view of the top-line numbers. It demands an understanding of the interplay between light and heavy grades, the nuances of regional trade flows, and the strategic maneuvers of key competitors. The PW Consulting Magnesium Carbonate Market Research Report is designed to provide this depth.
We invite stakeholders to utilize this overview as a foundation for their strategic planning. For the detailed segmentation data, comprehensive competitor profiles, and actionable forecasts required to navigate 2026 and beyond, we recommend accessing the full report. This ensures that your decisions are based on complete intelligence rather than partial visibility.
PW Consulting remains committed to delivering clarity in complex markets. For further inquiries or to acquire the full dataset, please contact our research team.
For detailed analysis of this topic, please visit the official page: Magnesium Carbonate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The Hemoperfusion Market in 2026: Strategic Intelligence for Executive Decision‑Making
A PW Consulting Market Research Introduction
Healthcare leaders and medical device strategists are operating in an environment where extracorporeal blood purification is transitioning from supportive intervention to central therapeutic modality. Our latest Hemoperfusion Market study is designed to convert that structural shift into actionable intelligence for 2026 planning cycles. Rather than delivering generic trend commentary, this report provides a disciplined framework for capital allocation, portfolio positioning, and competitive readiness.
The purpose of this preview is straightforward. We want you to understand the analytical rigor behind the study, see how macro momentum connects to on‑the‑ground business decisions, and recognize the practical tools embedded in the research. At the same time, we deliberately hold back the most granular figures here, because the full strategic value lies in the complete segmentation architecture, scenario modeling, and competitive mapping available in the published report.
Why 2026 Is a Defining Year for Hemoperfusion Strategy
The market has already crossed a meaningful inflection point. Over the 2020–2025 historical window, the industry expanded from roughly $550.15 million to $987.6 million, reflecting sustained demand for advanced toxin and metabolite clearance technologies. That pace is not slowing. Our forecast period from 2026 through 2032 projects continued expansion at a compound annual growth rate of 12.45% . Current-year market size is evaluated at approximately $1,145.02 million , with continued growth anticipated through the end of the forecast horizon as adoption broadens across critical care, hepatology, and toxicology settings.
For executives, the strategic implication is clear: 2026 is not simply another year of incremental growth. It is a decision window. Organizations that wait for the next cycle of mature consensus often expose themselves to pricing pressure, crowded distribution channels, and reactive product roadmaps. The companies that move now are doing so with a better map of where demand is concentrated, how regulatory pathways are evolving, and which technological platforms are gaining clinical credibility.
This study was built with that decision window in mind. It connects historical performance to forward-looking scenarios so you can evaluate not only what the market looks like today, but how the trajectory may unfold through 2032 and what that implies for manufacturing, partnerships, and commercial execution.
What the Research Delivers: Practical Intelligence, Not Just Top‑Line Numbers
A market study is only useful if it changes how teams spend time and capital. Our hemoperfusion research was designed to support cross-functional planning rather than sit passively on a shelf. The report integrates the following operational components:
- Segment-level demand architecture: The analysis breaks the market down along the dimensions that matter for product strategy, procurement planning, and clinical positioning. This allows you to see where revenue concentration is forming and where whitespace opportunities may emerge.
- Historical and forecast continuity: By pairing a ten-year historical view with a forward-looking projection to 2032, the study enables trend validation instead of reliance on single-year snapshots. That continuity is essential when you are evaluating whether a growth signal is durable or cyclical.
- Competitive positioning framework: The report examines how leading participants differentiate through technology platform, clinical indication focus, and distribution strategy. The goal is to help you interpret competitive moves in context rather than in isolation.
- Regulatory and compliance navigation: Because sorbent hemoperfusion systems are classified as Class II medical devices under 21 CFR 876.5870, with Premarket Approval or PDP requirements for hepatic coma and metabolic disturbance indications, regulatory strategy is not a side note. It is part of the commercial equation. The study addresses these dynamics so that compliance planning is incorporated into market entry and expansion decisions.
- Scenario-oriented planning inputs: The research is structured to support sensitivity discussions around adoption trajectories, indication mix, and regional execution priorities. This makes the output useful for both strategic planning and operational forecasting.
Each component is designed to answer a specific executive question: Where should we compete? What indications deserve the strongest commercial focus? Which technological approaches are most defensible? And how do regulatory and reimbursement realities shape the speed and shape of market entry?
Segmentation That Matters for Product and Commercial Strategy
The report’s segmentation is built to support decisions, not simply to describe the market. The starting point is the technology and material dimension, where the study examines the relative commercial footprint of Activated Carbon Hemoperfusion and Resin Hemoperfusion . These categories reflect different adsorbent behaviors, manufacturing considerations, and clinical utilization patterns, which means they carry distinct implications for R&D prioritization, supply chain strategy, and customer education.
From an application perspective, the research captures how clinical demand is distributed across indications including Hepatic Encephalopathy , Autoimmune Diseases , Drug Overdose , Specific Intoxications , and Others . This is critical because application mix directly influences procurement cycles, clinical evidence requirements, and the way a product story is positioned within hospital formularies and specialty departments. A portfolio that performs well in one indication may need a very different adoption plan in another.
The geographic dimension further sharpens the picture. The study maps demand across major regions including North America , Europe , Asia Pacific , Latin America , and Mideast and Africa . Regional analysis matters because market access patterns, institutional procurement behavior, and clinical adoption pathways differ materially from one geography to another. A strategy that assumes uniform global demand will almost always misallocate resources. By contrast, region-specific interpretation helps executives prioritize launch sequencing, distributor partnerships, and clinical engagement efforts.
Throughout the segmentation analysis, the report maintains a consistent discipline: it shows the structure that supports strategic choice without reducing the market to simplified rankings. For the complete quantitative breakdown across each segmentation axis, the published study provides the full detail necessary for internal modeling and investment justification.
Competitive Landscape: Five Players Shaping the Market
No market analysis is complete without a credible view of the firms setting the pace. In hemoperfusion, the competitive landscape is defined by a mix of specialized innovators, established healthcare companies, and firms with deep polymer and blood-contact material expertise. The study focuses on five companies whose strategic positioning has meaningful implications for the broader market:
Disposable Hemoerfusion Cartridge Market
Spectral Medical Inc.
Headquartered in Toronto, Canada, Spectral Medical is focused on Toraymyxin™, a therapeutic hemoperfusion device designed for endotoxin removal in endotoxic septic shock. Its clinical emphasis reflects a broader industry movement toward targeted sorbent therapies in critical care. Our analysis examines how this focus influences clinical adoption, indication positioning, and the regulatory context surrounding high-acuity therapeutic use.
Jafron Biomedical Co., Ltd.
Based in Zhuhai, Guangdong, China, Jafron Biomedical develops the HA series of disposable hemoperfusion cartridges for blood purification in renal, liver, and intoxication treatments. The company’s disposable cartridge model illustrates an important commercial dynamic: modularity, ease of use, and cost-conscious procurement can be decisive in emerging adoption environments. The report places this strategy within the larger context of regional demand and affordability-driven purchasing.
Baxter International Inc.
Deerfield, Illinois-based Baxter is engaged in integrated extracorporeal blood purification and hemoperfusion systems as part of its renal care portfolio. Its presence underscores the role of broader portfolio integration in competitive positioning. When hemoperfusion fits into a larger platform strategy, the commercial narrative often shifts from single-product performance to system-level clinical value, service capability, and hospital workflow compatibility. This study examines that integration angle in depth.
Asahi Kasei Corporation
Tokyo-based Asahi Kasei brings a strong orientation toward resin-based hemoperfusion technologies and polymer chemistry for blood purification applications. For a market where adsorbent material performance directly affects product efficacy and competitive differentiation, this expertise is strategically significant. Our analysis addresses how material science leadership translates into product positioning and long-term defensibility in a technology-driven category.
CytoSorbents Corporation
CytoSorbents, based in Monmouth Junction, New Jersey, focuses on CytoSorb® hemoadsorption cartridges for cytokine and toxin removal in critical care. Its position highlights the growing attention to immunomodulation and toxin clearance in acute care settings. The report evaluates this positioning as part of the broader competitive conversation around which clinical benefits are most credible, most repeatable, and most commercially actionable.
Together, these companies represent a cross-section of strategic approaches: indication-specific therapeutics, disposable platform expansion, portfolio integration, material science leadership, and critical care-focused adsorption. The report goes beyond company-level description to examine how these strategies interact, where they compete directly, and where each is more likely to shape downstream purchasing behavior.
Recent Developments and Regulatory Dynamics
Market intelligence must be current to be credible. One notable recent event is Spectral Medical’s May 2026 Premarket Approval submission to the U.S. FDA for the Toraymyxin™ hemoperfusion device to treat endotoxic septic shock. From a strategic standpoint, PMA activity in this category is not a narrow regulatory milestone; it signals momentum in high-acuity indications and draws attention to the broader intersection of clinical evidence, regulatory clearance, and commercialization timing.
At the same time, the regulatory environment continues to shape how products move through the pipeline. Sorbent hemoperfusion systems are classified as Class II medical devices under 21 CFR 876.5870, with PMA or PDP requirements for hepatic coma and metabolic disturbance indications. That regulatory architecture influences not only product approval timing but also evidence generation strategy, label positioning, and the resourcing needed to compete in more tightly regulated indications. Companies that underestimate those requirements can misjudge both time-to-market and commercial scope.
Our study incorporates these regulatory dynamics so that market analysis remains grounded in real pathway constraints rather than abstract adoption curves. This is especially important for firms evaluating entry into indications where clearance requirements and clinical expectations are closely linked.
What This Means for Enterprise Strategy in 2026
The central question for leadership teams is how to translate market momentum into durable advantage. Based on the direction of this research, several strategic priorities stand out:
- Clarify the indication battleground. The application mix in this category is not uniform, and commercial success will depend on where a company chooses to focus clinical evidence, sales engagement, and service support. Broad claims rarely outperform focused, defensible positioning.
- Align product design with adoption economics. Whether the opportunity lies in disposable cartridges, integrated systems, or specialized therapeutic devices, the purchasing environment is shaped by procurement cycles, facilities’ workflow preferences, and cost-conscious evaluation. Design choices and commercial packaging should reflect that reality.
- Treat regulatory strategy as competitive strategy. Because indications such as hepatic coma and metabolic disturbance carry specific regulatory requirements, the approval pathway is not merely compliance work. It is a strategic determinant of how quickly a product can scale and where it can credibly compete.
- Plan around concentration and competition without overgeneralizing. The market is not a monolith, and competitive intensity varies by segment and geography. Understanding where concentration is high and where the field remains more open helps companies choose whether they should pursue differentiation, scale, partnership, or selective entry.
- Use the forecast as a scenario tool, not a promise. The 2026–2032 outlook provides a framework for thinking about trajectory, but its real value lies in supporting sensitivity analysis. Good strategy accounts for multiple demand paths, not a single assumed future.
Why the Full Study Is Designed for Action, Not Just Awareness
This preview has outlined the architecture of the analysis, the market momentum behind it, and the competitive and regulatory forces shaping 2026 decision-making. The goal has been to demonstrate depth without giving away the exact data points and detailed breakdowns that your internal teams will need to act with confidence. That is intentional.
Hemoperfusion Market
In practice, the most valuable insights are often the ones that require full segmentation detail, structured company evaluation, and cross-indication interpretation. Those are the materials that support board discussion, R&D prioritization, partnership evaluation, and commercial planning in a disciplined way. The executive preview can show you the logic of the market; the complete study gives you the numbers and the structured view needed to turn that logic into a real plan.
For organizations preparing for the rest of 2026 and beyond, the strategic question is no longer whether hemoperfusion is expanding, but where to position, how to move, and what evidence and compliance commitments will shape the outcome. PW Consulting’s Hemoperfusion Market research is built to help leaders answer those questions with precision.
Begin With the Full Intelligence Package
The complete market study provides the detailed segmentation architecture, competitive mapping, regulatory interpretation, and scenario inputs needed to support concrete 2026 decisions. If your organization is evaluating product strategy, market entry, partnership options, or commercial prioritization in hemoperfusion, the full report is the appropriate foundation for that work. This preview is intended to show that the analysis is grounded, structured, and ready for executive use, while leaving the most actionable detail available in the published intelligence.
For detailed analysis of this topic, please visit the official page: Hemoperfusion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Device Market Hits $572.31B in 2025, Projected to Reach $889.27B by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-16
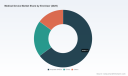
Navigating the Next Wave: Strategic Intelligence for the 2026 Medical Device Landscape
The global medical device industry stands at a critical inflection point. Between 2020 and 2025, the market expanded from approximately USD 424.76 billion to USD 572.31 billion, demonstrating resilience despite supply chain disruptions, regulatory recalibrations, and shifting reimbursement frameworks. As we enter the 2026-2032 forecast period, the trajectory points toward sustained expansion, with a projected compound annual growth rate of 6.98 percent. By 2032, the global market is expected to approach USD 889.27 billion. For executive teams, investors, and strategic planners, these headline figures represent more than macroeconomic momentum. They signal structural shifts in how devices are developed, regulated, distributed, and adopted across care settings.
At PW Consulting, we have synthesized years of historical tracking, primary research, and forward-looking scenario modeling into a comprehensive Medical Device Market intelligence report. This publication is designed not as a static data dump, but as a decision architecture tool. The following overview outlines the strategic value embedded in the analysis, the operational depth covered, the competitive forces reshaping the sector, and the regulatory and reimbursement currents that will define execution risk in 2026 and beyond.
Why 2026 Demands a Structured Intelligence Framework
The current operating environment is defined by simultaneous pressures and opportunities. On the regulatory front, compliance expectations have tightened across major markets. The FDA's Quality Management System Regulation became fully effective in early 2026, replacing legacy requirements and formally aligning U.S. expectations with ISO 13485:2016. This transition is not merely administrative; it reshapes documentation workflows, supplier qualification processes, and post-market surveillance architectures for manufacturers operating at scale. Across the Atlantic, the European Union's EUDAMED transition deadline for new medical device products has introduced additional registration, traceability, and transparency obligations under the MDR and IVDR frameworks. Companies that treat these milestones as isolated compliance checkboxes risk underestimating the operational redesign required to maintain market access.
Reimbursement dynamics are equally consequential. The CPT 2026 code set, effective January 1, added 288 new codes, including provisions for remote patient monitoring and leg revascularization procedures. These updates expand the billing vocabulary for clinically advanced interventions, but they also require manufacturers and providers to align product positioning, clinical evidence packages, and coding strategies with evolving payer expectations. In parallel, FDA 510(k) review times averaged 140 to 175 days in 2025, with a significant majority of submissions exceeding the 90-day target. For product teams, this reality compounds time-to-market planning, cash flow forecasting, and portfolio sequencing decisions.
Medical Device Market
These forces do not operate in isolation. They interact with capital allocation choices, hospital procurement cycles, and the growing cost burden of advanced clinical infrastructure. Systems such as surgical navigation platforms now represent significant capital commitments for provider organizations, influencing adoption pacing and vendor selection criteria. In this environment, executives need a structured view of where growth is concentrated, how segments are evolving, and which strategic levers will differentiate performers from laggards.
What the Report Delivers: Operational Depth for Cross-Functional Teams
The Medical Device Market report is structured to support multiple functional perspectives without sacrificing analytical rigor. Rather than offering a single aggregated view, the study disaggregates the market across dimensions that matter for strategy, forecasting, and resource allocation. The segmentation architecture includes product categories, end-user settings, and regional distribution, allowing readers to isolate the drivers most relevant to their portfolios.
For commercial and market access leaders, the report maps the end-user landscape across hospitals and ambulatory surgery centers, clinics, and other care environments. This breakdown is essential for understanding purchase dynamics, procurement cycles, and the differing adoption curves that characterize large institutional buyers versus smaller outpatient settings. For product and R&D stakeholders, the type-based segmentation illuminates where innovation activity is concentrated, how clinical needs are translating into commercial categories, and which segments are attracting incremental investment.
The regional analysis provides a geographic lens on demand patterns, market maturity, and distributional variance across major territories. Rather than treating geography as a static backdrop, the report uses it to frame localization strategy, pricing architecture, regulatory pathway planning, and partnership considerations. The inclusion of a detailed forecast window through 2032 enables scenario planning that accounts for both baseline growth trajectories and potential disruption points.
Beyond segmentation, the publication integrates competitive intelligence, recent regulatory and industry developments, and contextual factors that shape execution. This combination allows strategy teams to translate high-level market size and growth metrics into actionable implications for channel design, launch sequencing, pricing strategy, and partnership evaluation.
Key Structural Themes Explored
- How product-category growth rates diverge across the forecast horizon and what that implies for portfolio prioritization
- The evolving role of hospitals and ambulatory settings as the dominant demand centers, alongside the growing relevance of clinics and specialized care environments
- Regional demand distribution and its implications for market entry, expansion pacing, and localization of commercial operations
- The relationship between regulatory transitions, reimbursement expansion, and the commercial viability of advanced device categories
- Capital intensity considerations that influence provider adoption and vendor competitiveness in high-investment clinical segments
Competitive Landscape: Concentration, Differentiation, and Strategic Posture
The medical device sector remains characterized by a concentrated yet diverse competitive field. Analysis of market concentration indicates that the top three players account for approximately 37.45 percent of total revenue, while the top five capture roughly 50.23 percent. This structure suggests a market where scale advantages, brand trust, and installed-base dynamics matter significantly, yet where specialized innovators and category leaders can still command meaningful positions through clinical differentiation and targeted commercial execution.
Several established corporations anchor the competitive core. Abbott Laboratories continues to build on its diagnostic device expertise, including blood glucose monitoring and molecular diagnostics. Medtronic maintains a broad footprint across implantable cardiac devices, insulin pumps, and neurostimulation systems. Johnson & Johnson operates across orthopedics, interventional cardiology, and minimally invasive surgical tools, while Becton, Dickinson and Company maintains a strong position in syringes, catheters, and vascular access systems. Stryker Corporation is closely associated with orthopedic implants, surgical robotics, and neurotechnology, and GE Healthcare remains a central force in medical imaging equipment and ultrasound systems. Baxter International Inc. contributes significant scale in infusion systems, dialysis machines, and hemodialysis solutions, while Boston Scientific advances in cardiac rhythm management, endoscopy, and neuromodulation. Siemens Healthineers and Danaher Corporation extend the competitive field through imaging, laboratory diagnostics, and biopharma-adjacent tool sets. Edwards Lifesciences remains focused on heart valve replacement and repair, and Zimmer Biomet Holdings continues to strengthen its joint reconstruction and musculoskeletal offerings.
Medical Textiles Market
Beyond the largest incumbents, a broad set of specialized players shapes category-level competition. Terumo Corporation advances cardiovascular and endovascular devices; Smith & Nephew competes in advanced wound care and orthopedics; Intuitive Surgical is closely identified with robotic-assisted surgery systems; and 3M maintains a diversified presence in infection prevention, wound care, and sterilization products. B. Braun, Alcon, Cardinal Health, and AmerisourceBergen add further depth across infusion therapy, ophthalmic instruments, distribution, and supply chain services. Hologic focuses on diagnostic imaging and women's health devices, Carestream Health on medical imaging and radiography systems, and ResMed on sleep apnea devices and respiratory therapy. Dexcom has become a defining name in continuous glucose monitoring, while Nipro Corporation, Biomerieux, Sonova Holding, Straumann, QuidelOrtho, Envista, and Carl Zeiss Meditec each anchor important niches ranging from dialysis and injectables to in vitro diagnostics, audiology, dental implants, point-of-care diagnostics, and ophthalmic systems.
This competitive mosaic matters because market leadership is not uniform across categories. The report examines how companies position themselves relative to category growth, regulatory complexity, reimbursement exposure, and technological change. Rather than presenting a simple ranking, the analysis considers the strategic logic behind portfolio focus, geographic reach, and innovation intensity. Recent developments reinforce this dynamic view of competition. For example, Bright Uro received FDA 510(k) clearance in mid-2026 for its Glean Abdominal Sensor, expanding multi-channel urodynamic capabilities for wireless ambulatory studies in lower urinary tract dysfunction. At the same time, the Medical Device Manufacturers Association hosted an FDA Forum with more than 125 attendees, where senior FDA officials addressed regulatory topics including biocompatibility, cybersecurity, and AI. The FDA also scheduled a hybrid regulatory education conference later in the year to discuss innovative strategies for medical devices, drugs, and biologics. These events illustrate a sector where regulatory engagement, technological novelty, and clinical differentiation are increasingly intertwined.
Regulatory, Reimbursement, and Infrastructure Dynamics
Strategic planning in 2026 cannot rely on product performance alone. The environment is being reshaped by overlapping regulatory harmonization, reimbursement expansion, and infrastructure cost realities. The full effectiveness of the FDA's QMSR marks a structural shift toward ISO-aligned quality systems, which affects documentation, supplier management, and audit readiness across the device lifecycle. In Europe, EUDAMED transition requirements for new products add another layer of registration and transparency obligations that influence launch timing and market access planning.
Reimbursement developments are expanding the procedural and service vocabulary that supports device adoption. The addition of new CPT codes for remote patient monitoring and leg revascularization procedures reflects broader trends toward continuous care models and minimally invasive intervention. These changes can improve the commercial feasibility of technologies that align with evolving care pathways, but they also require manufacturers to maintain robust evidence generation, coding alignment, and payer engagement strategies.
At the provider level, capital intensity remains a practical constraint. Advanced surgical navigation systems can represent significant investments for hospitals, with costs that influence procurement timing, service contracts, and total cost of ownership calculations. As providers evaluate technology purchases, the value proposition increasingly depends on workflow integration, training support, sterilization and maintenance considerations, and demonstrable clinical and operational outcomes. For manufacturers, this means commercialization strategies must address not only product performance but also the economic and operational realities of the purchasing organization.
Regulatory review timelines further shape planning assumptions. With FDA 510(k) review times averaging well above the 90-day target in 2025, product teams and executive sponsors need realistic expectations for submission cycles, supplemental filings, and post-clearance execution. Integrating these operational realities into forecast models and launch plans is essential for avoiding over-optimistic timing assumptions.
Translating Market Intelligence into 2026 Decision Advantage
The overarching value of this report lies in its ability to connect macroeconomic growth signals with the operational decisions that determine competitive outcomes. The market's projected expansion from roughly USD 613.56 billion in 2026 to nearly USD 889.27 billion by 2032 is not a uniform ascent. It is distributed unevenly across product categories, care settings, and regions, and it is mediated by regulatory timing, reimbursement clarity, and provider capital behavior. Executives who understand these distributions can make better-informed choices about where to invest, how to sequence launches, which partnerships to pursue, and where to strengthen compliance and market access capabilities.
For portfolio strategy teams, the segmentation and forecast framework supports prioritization decisions by highlighting where demand trajectories are strongest and where competitive density is likely to intensify. For commercial leaders, the end-user and regional analysis informs channel design, pricing strategy, and go-to-market localization. For regulatory and quality functions, the contextual updates on QMSR, EUDAMED, and 510(k) review dynamics provide a practical backdrop for resource planning and risk management. For corporate development and investor relations teams, the competitive concentration data and company-level profiles offer a structured basis for benchmarking, partnership screening, and market positioning narratives.
The report also emphasizes the importance of monitoring near-term signals that can alter longer-term assumptions. Recent regulatory education initiatives, FDA engagement forums, and clearance activity point to an environment where innovation and oversight are evolving together. Companies that build processes to interpret these signals quickly will be better positioned to adjust development roadmaps, update market access strategies, and align internal timelines with external realities.
Conclusion: From Insight to Execution
The medical device market is entering a phase where growth is substantial but increasingly conditional on strategic precision. The broad expansion reflected in the forecast period is real, yet its value accrues to organizations that can interpret segment-level dynamics, navigate regulatory and reimbursement change, and align commercial execution with the economic constraints of provider buyers. PW Consulting's Medical Device Market report is designed to give decision-makers that interpretive edge.
To explore the full segmentation detail, regional breakdowns, competitive profiles, and forecast scenarios, we invite you to access the complete report on our website. The comprehensive intelligence package provides the depth required to translate market momentum into disciplined, high-conviction strategy for 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Medical Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com